


Why Some AI Startup Models Are Losing Momentum, According to Google’s Startup Chief
The explosive rise of generative AI triggered a gold-rush moment for startups, with new ventures seemingly launching by the minute. But as the market matures, not all business models born during the boom are proving resilient. According to a senior Google executive, two once-popular approaches are now flashing warning signs: LLM wrappers and AI aggregators.
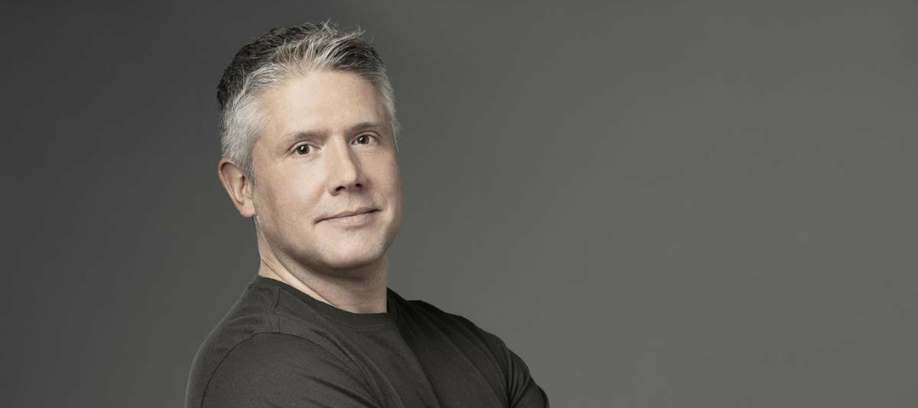
Darren Mowry, who leads Google’s global startup organization across Google Cloud, DeepMind, and Alphabet, believes founders relying on these models should pause and reassess. He describes such startups as having their “check engine light” on.
The Growing Risk for LLM Wrapper Startups
LLM wrappers are companies that build products by layering a user interface or experience on top of existing large language models such as GPT, Claude, or Gemini. These tools often target specific use cases—like helping students study or assisting professionals with writing or analysis.
However, Mowry warns that simply packaging an existing model is no longer enough.
“If you’re really just counting on the back-end model to do all the work and you’re almost white-labeling that model, the industry doesn’t have a lot of patience for that anymore,” Mowry said on this week’s episode of Equity.
He adds that startups relying on minimal differentiation are unlikely to scale.
Wrapping “very thin intellectual property around Gemini or GPT-5” signals you’re not differentiating yourself, Mowry says.
To succeed, founders must create defensible advantages.
“You’ve got to have deep, wide moats that are either horizontally differentiated or something really specific to a vertical market” for a startup to “progress and grow,” he said.
Examples of LLM-driven companies that have managed to build such moats include Cursor, a GPT-powered coding assistant, and Harvey AI, which focuses on legal professionals.
The days when startups could gain traction simply by placing a new interface on top of GPT—particularly during the mid-2024 launch of OpenAI’s ChatGPT store—are fading. Today, sustainable value creation has become the real test.
Why AI Aggregators Face Structural Challenges
AI aggregators represent a subcategory of wrappers. These startups combine multiple LLMs into a single interface or API, allowing users to route queries across different models. Many also offer orchestration features such as monitoring, governance, or evaluation tools.
Notable examples include Perplexity and OpenRouter, which provides developers with access to multiple AI models through one API.
Despite early traction, Mowry’s guidance for new founders is blunt:
“Stay out of the aggregator business.”
He argues that growth has slowed because customers now expect more than access or routing efficiency.
Users want “some intellectual property built in” to ensure queries are matched to the right model for the right reason—not simply because of backend infrastructure or compute availability.
Lessons from the Early Cloud Computing Era
Mowry’s perspective is shaped by decades of experience in cloud computing, having previously worked at AWS and Microsoft before joining Google Cloud. He sees strong parallels between today’s AI market and the early cloud era of the late 2000s and early 2010s.
Back then, numerous startups attempted to resell AWS infrastructure, positioning themselves as simplified gateways with added billing, tooling, and support. As Amazon expanded its own enterprise features and customers became more cloud-savvy, most of these intermediaries disappeared.
Only companies that added meaningful services—such as security, migration support, or DevOps consulting—survived.
AI aggregators today, Mowry suggests, face similar margin pressure as model providers increasingly build enterprise-grade capabilities themselves, reducing the need for middle layers.
Where Mowry Sees Strong Growth Ahead
Despite his cautionary outlook on certain AI models, Mowry remains optimistic about other segments of the tech ecosystem.
He highlighted vibe-coding and developer platforms as standout performers, noting that 2025 was a record-breaking year for the sector. Startups such as Replit, Lovable, and Cursor—all Google Cloud customers, according to Mowry—have attracted significant investment and user adoption.
He also expects continued momentum in direct-to-consumer AI, particularly where powerful tools are placed directly in users’ hands. One example is Google’s AI video generator Veo, which Mowry sees as a compelling tool for film and TV students looking to bring creative ideas to life.
Beyond AI: Biotech and Climate Tech Take the Spotlight
Looking past AI, Mowry believes biotech and climate tech are entering a strong growth phase. He points to increasing venture investment and unprecedented access to large datasets as key drivers.
These industries, he says, are now able to create real-world value using data at a scale that simply wasn’t possible before—unlocking innovation “in ways we would never have been able to before.”
0 Comments